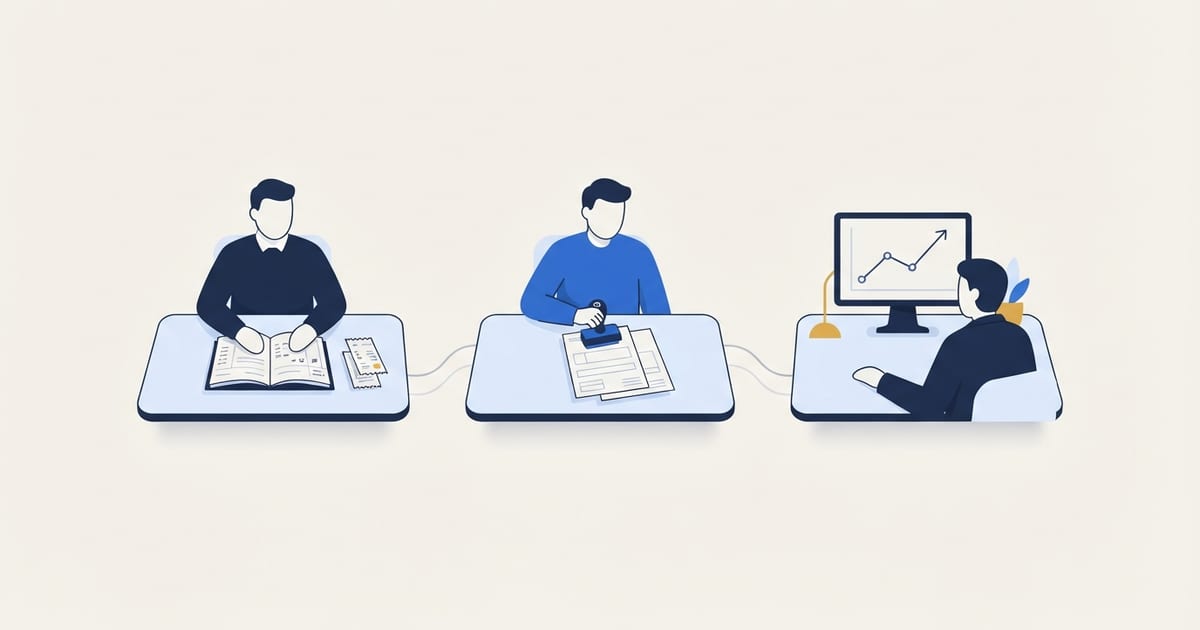
A bookkeeper records what happened. An accountant, usually a CPA, turns those records into tax filings and keeps you compliant. A fractional CFO uses the same records to plan what happens next. Most small businesses need all three eventually, and they need them in that order.
That is the short answer. The longer one matters because owners hire these roles out of order all the time, and each mistake costs money in a different way.
The Short Version
| Bookkeeper | Accountant or CPA | Fractional CFO | |
|---|---|---|---|
| Question it answers | What happened? | What do we owe, and what do we file? | What should we do next? |
| Looks at | Every transaction | The year as a whole | The next 3 to 12 months |
| Produces | Reconciled books, monthly P&L and balance sheet | Tax returns, tax planning, year-end adjustments | Cash forecast, budget, pricing and margin analysis |
| How often | Weekly or monthly | A few times a year | Monthly, plus when a decision comes up |
| You need it when | You have transactions | You owe taxes | Your decisions outgrow your bank balance |
What a Bookkeeper Does
A bookkeeper keeps the record accurate. That means categorizing every transaction, reconciling every bank and credit card account to the statement, tracking what customers owe you and what you owe vendors, and closing each month so the reports mean something.
The output is a set of books you can trust: a profit and loss statement, a balance sheet, and a list of open invoices and bills that match reality. If you want to know what those reports tell you, we wrote a guide to the financial reports every small business owner should know.
Bookkeeping is not the same as having a bank feed connected to QuickBooks. Transactions flowing in automatically is data entry, and a lot of it lands in the wrong place. We covered the gap in why auto-synced transactions are not bookkeeping.
What an Accountant or CPA Does
An accountant works from the books to produce what the government and your lenders need: tax returns, year-end adjustments, depreciation schedules, and sometimes reviewed or audited financial statements. A good one also does tax planning, which is where the real value is. Planning happens before the year ends. Filing happens after, when most of the decisions are already locked in.
The most common frustration owners have with their CPA is that the CPA only sees the business once a year, in March or April, after everything has happened. That is not a CPA problem. That is what the role is built for. Asking your tax preparer to also be your monthly bookkeeper and your financial planner usually means paying tax-season rates for cleanup work. There is more on where the line sits in bookkeeping vs. accounting.
What a Fractional CFO Does
A fractional CFO is a part-time finance leader. You get the forward-looking work a full-time CFO would do, for a few hours a month instead of a full salary.
In practice that work looks like this:
- Cash flow forecasting. A week-by-week view of cash coming in and going out, so you see a tight month coming instead of discovering it on payday. We walk through how to build one in how to build a 13-week cash flow forecast.
- Monthly financial review. Not just sending the reports, but explaining what changed and why it matters.
- Pricing and margin analysis. Which services, jobs, or customers actually make money. Almost every owner is surprised by at least one of them.
- Budgeting and scenarios. What happens to cash if you hire, sign the lease, buy the truck, or lose your biggest customer.
- Decision support. Someone to call before you commit to something, not after.
The key word is forward. A bookkeeper and a CPA are both mostly looking back. A fractional CFO is looking at the next quarter and the next year.
Where Owners Get This Wrong
Hiring for the future before the past is accurate. A forecast built on messy books is a confident wrong answer. If your accounts are not reconciled or your categories are a guess, planning work will produce numbers that look precise and are not. The cleanup comes first.
Expecting the tax preparer to run the finances. If the only financial conversation you have all year is with your CPA in April, nobody is looking at cash, margins, or pricing during the eleven months when you could still change them.
Treating the bank balance as the forecast. This is the most common one. The balance tells you what you have today. It does not tell you that three payrolls land in October, that the insurance renewal is due in November, or that your best customer has quietly started paying in 60 days instead of 30. We wrote about how a business can be profitable on paper with no cash in the bank, and it almost always comes down to this.
Which One Do You Need First?
Work through it in order:
- If your books are behind, unreconciled, or you are not sure they are right: start with bookkeeping. Nothing else works until this does. Our guide on when to hire a bookkeeper covers the signs.
- If you owe taxes and do not have a tax professional: get one. This is not optional, and it is not something to learn from videos.
- If the books are clean and taxes are handled, but you are making big decisions from the bank balance: that is the point where a fractional CFO pays for itself. Common triggers are a hire, a lease, a loan, a price change, a second location, or revenue growing while cash feels tighter.
For a lot of businesses somewhere between $500K and $5M in revenue, the honest answer is that bookkeeping and tax are covered but nobody owns the forward view. That gap is what the fractional role is for.
Can One Firm Do More Than One of These?
Yes, and it often works better that way. The person forecasting your cash is far more useful when they are also the person who knows why last month's numbers look the way they do.
That is how we set it up at Pinstripe. We do the bookkeeping, and for clients who need the planning layer, we add fractional CFO services on top of books we already know are right. We work alongside your CPA rather than replacing them, and your CPA gets clean, reconciled records at year end instead of a shoebox.
Frequently Asked Questions
Is a fractional CFO the same as a controller?
Not quite. A controller owns the accuracy of the books and the month-end close. A CFO owns planning, cash strategy, and decisions. In a small business one person may cover parts of both, but if you are hiring for one, be clear about which problem you are solving.
Do I need a CPA if I have a bookkeeper?
Usually yes. A bookkeeper keeps the record. Filing business tax returns and planning around tax law is a separate skill, and the bookkeeper's job is to hand your tax professional a clean set of books.
How many hours does a fractional CFO work for a small business?
Typically a few hours a month, built around a monthly review and a rolling forecast, with more time when a big decision is on the table. It is part-time by design.
Is a fractional CFO worth it for a small business?
It is worth it when the decisions in front of you are bigger than the cost of the help: a hire, a lease, a loan, a pricing change. If the books are not clean yet, it is not worth it yet. Fix the foundation first.
If you are not sure which of these you are missing, that is a normal place to be. We work with small businesses across Long Island and remotely, and we will tell you honestly whether you need a fractional CFO or whether clean books get you most of the way there. Book a free consultation.
Free download, no email required
Year-End Close & 1099 Kit
A November-to-January close timeline, the 1099 rules in plain English, and a vendor tracker that flags who needs a form.
How to use it